
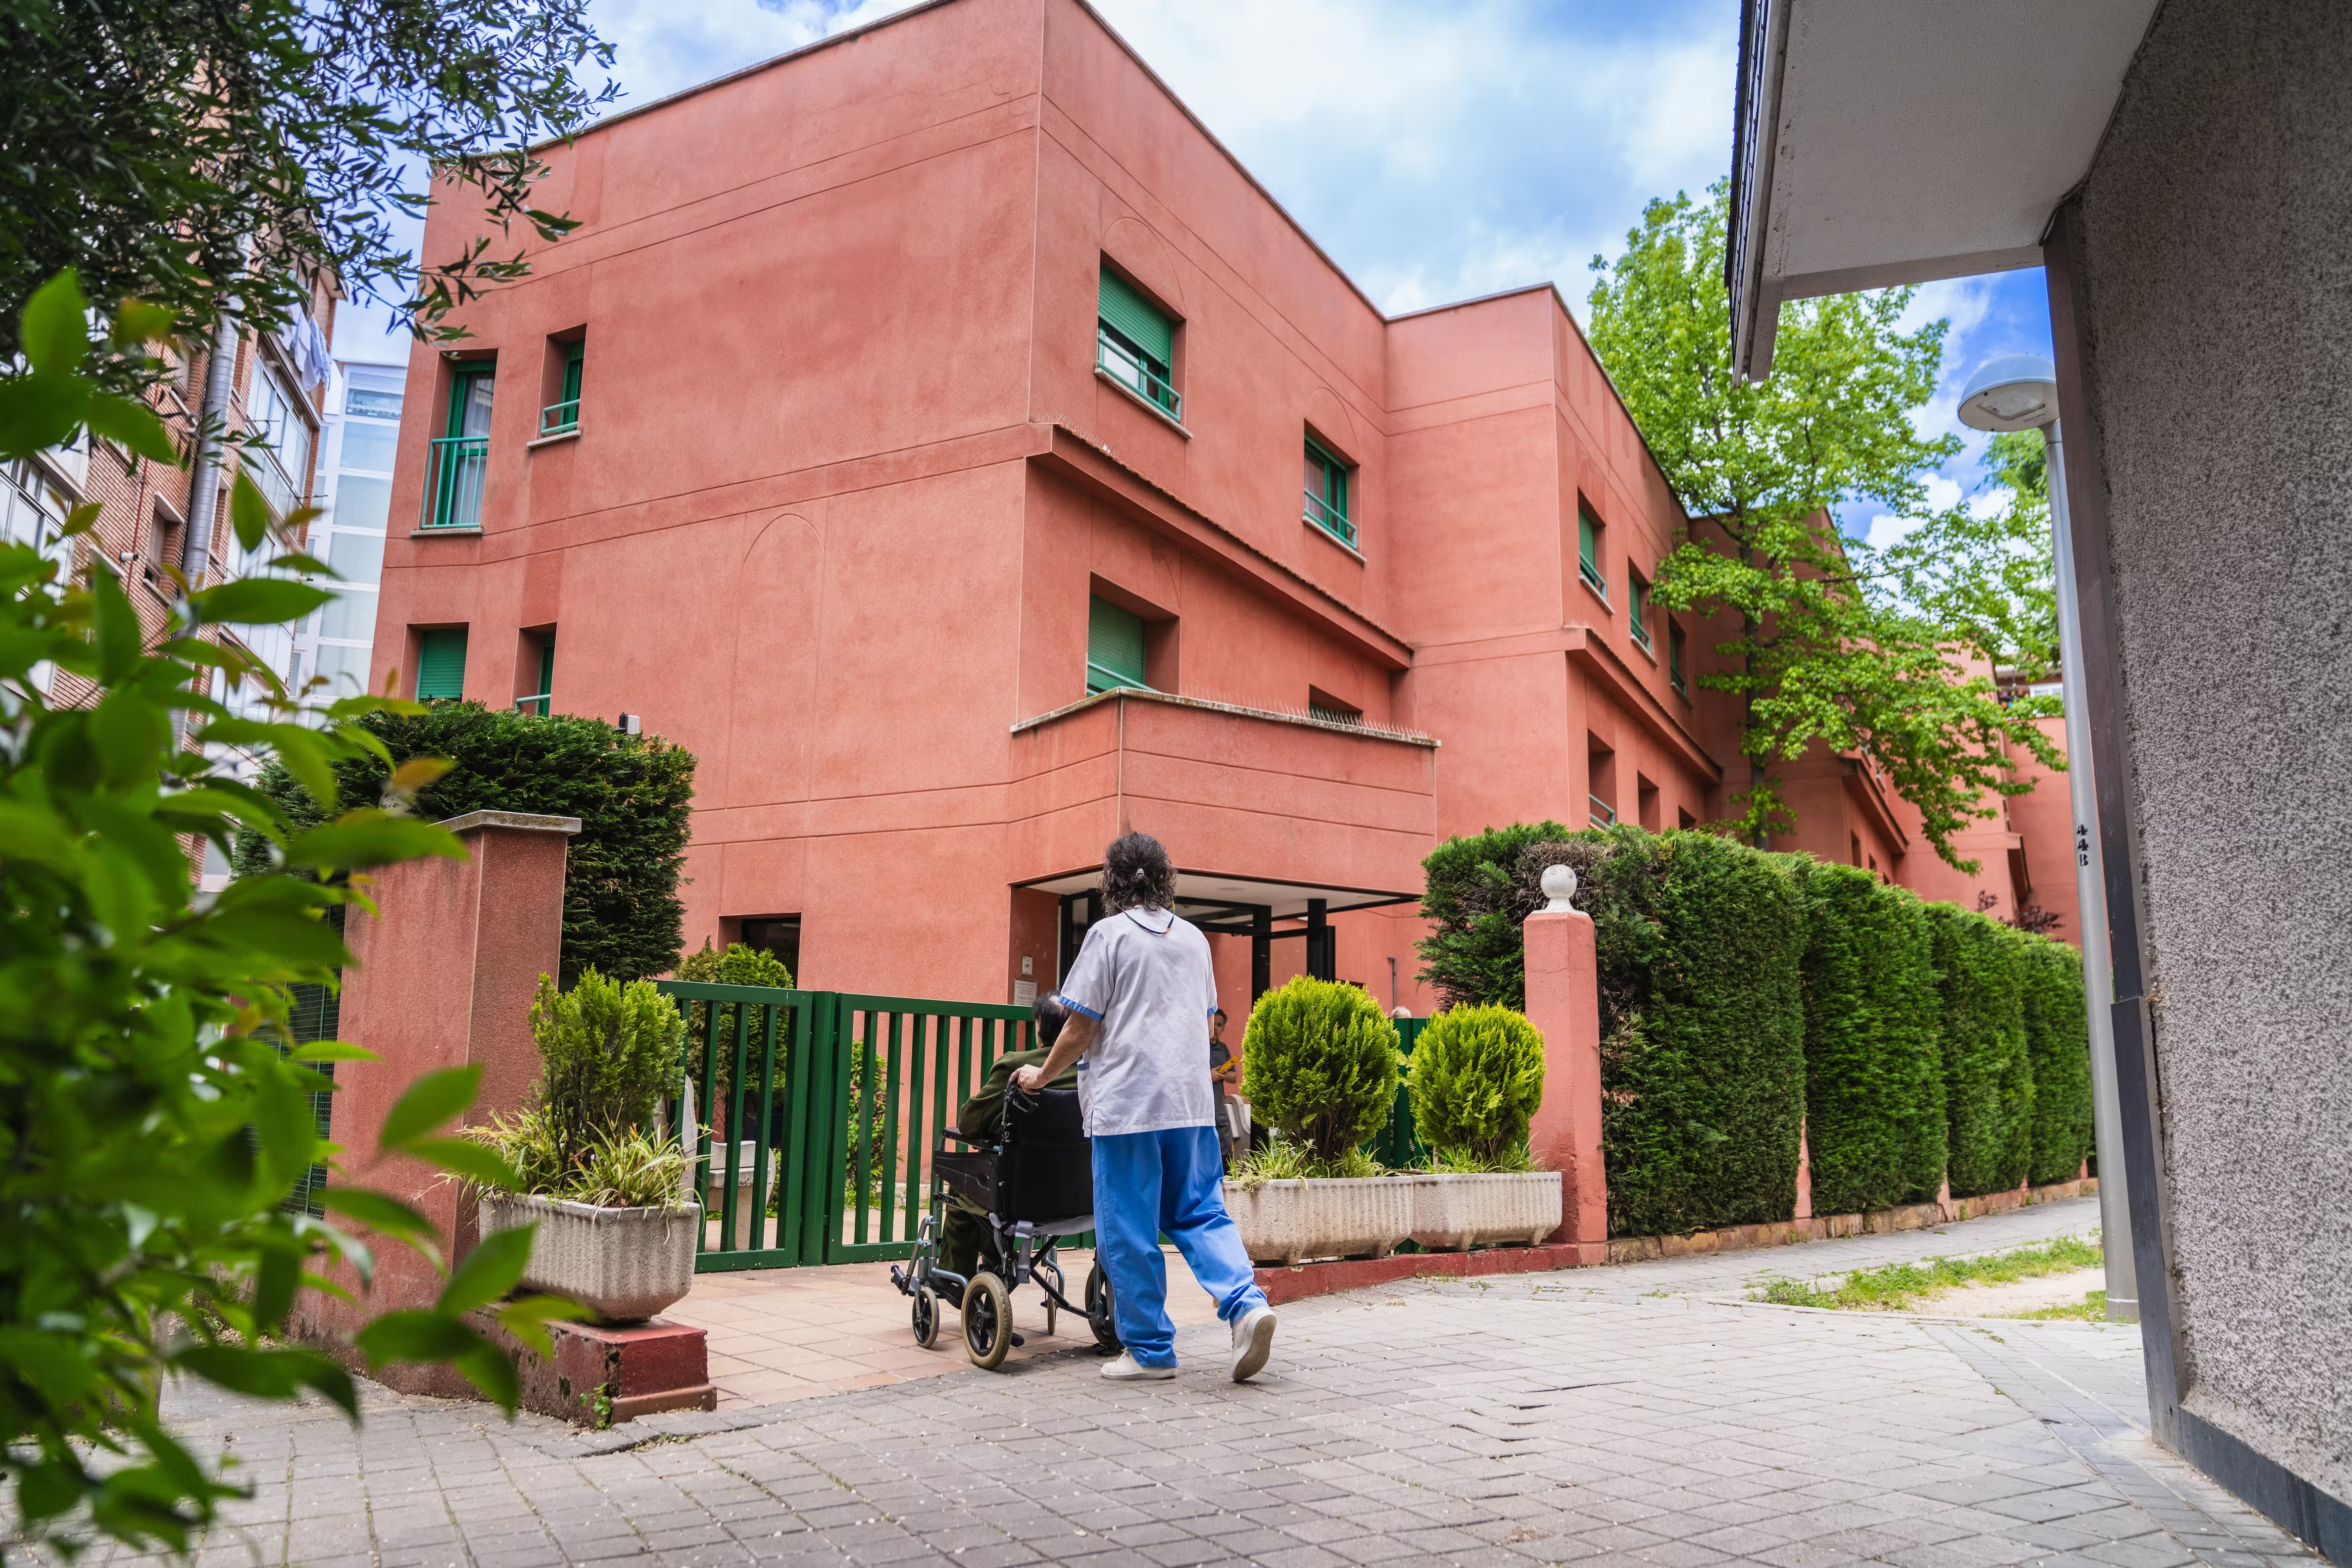
A reinstatement cost assessment calculates how much it would cost to completely rebuild your care home following a total loss. It helps ensure your buildings insurance reflects the true rebuilding cost of the property, reducing the risk of underinsurance and a potential shortfall at claim stage.
Many care providers assume their buildings insurance reflects the true cost of rebuilding their property. However, construction costs, specialist care facilities, regulatory requirements and market changes can mean a building is insured for significantly more or less than it should be.
At Quality Care Group, we help care providers obtain professional reinstatement cost assessments so they can arrange the appropriate level of buildings insurance and reduce the risk of underinsurance.
What Is a Reinstatement Cost Assessment?
A reinstatement cost assessment (RCA) calculates the amount required to rebuild your property from the ground up following a major insured event such as fire, flood or structural collapse.


Why Care Homes Are Particularly Vulnerable to Underinsurance
Care homes are often more complex than standard commercial properties.
Buildings frequently contain:
- Passenger lifts
- Accessible bathrooms and bedrooms
- Nurse call systems
- Commercial kitchens
- Fire protection systems
- Specialist medical and care infrastructure
These features can substantially increase rebuilding costs compared with conventional residential or commercial buildings.
Without regular reviews, many care home owners find their declared sums insured no longer reflect today's construction and reinstatement costs.
If a care home is underinsured, an insurer may reduce the amount paid on a claim in proportion to the level of underinsurance, depending on the policy wording.
What Is the Average Clause?
Many insurers apply something known as the Average Clause.
If your building is underinsured, an insurer may reduce a claim payment proportionately, even if the claim itself is smaller than the total sum insured.
For example:
- Your care home should be insured for £4 million
- The building is insured for only £3 million
- The property is therefore insured for 75% of its true reinstatement value
If a £1 million claim occurs, the insurer may only pay £750,000, leaving the business responsible for the remaining £250,000.
This is why obtaining an accurate reinstatement cost assessment is so important.
RebuildCostAssessment.com highlights the Average Clause as one of the most common causes of insurance shortfalls for property owners.
Signs Your Care Home May Need a Reinstatement Cost Assessment
You should consider an assessment if:
Your building has never had a professional reinstatement valuation
The assessment is more than three years old
Significant refurbishment works have been completed
Capacity has been expanded
Construction costs have increased significantly since the last review
Your insurer or lender has requested an updated valuation
You are purchasing a new care home
Our Reinstatement Cost Assessment Service
Through our specialist partners, we can arrange professional reinstatement cost assessments for:
- Care homes
- Nursing homes
- Residential care facilities
- Supported living properties
- Children's homes
- Healthcare premises
- Multi-site care groups
Assessments can often be completed using desktop information, while more complex properties may require a site visit.
Why Choose Quality Care Group?
Specialists
We work exclusively with care and healthcare providers and understand the unique characteristics of care home buildings.
We help ensure your insurance programme reflects the true rebuilding cost of your property.
Expertise
We work with experienced professionals who understand building reinstatement valuations and insurance requirements.
A reinstatement cost assessment forms part of a wider risk management strategy that helps protect your business, residents and financial position.
FAQs
Reinstatement values should be reviewed regularly and following significant refurbishment, extensions or major changes in construction costs. The appropriate frequency will depend on the property plus insurer requirements.
No. Market value reflects factors such as location, land value plus demand. Reinstatement value estimates the cost of rebuilding the property following a total loss.
A reinstatement cost assessment calculates the estimated cost of rebuilding a care home following a total loss, including construction costs, demolition, professional fees and compliance with current building regulations.
If a care home is underinsured, an insurer may reduce a claim payment depending on the policy terms. This could leave the provider responsible for a significant proportion of repair or rebuilding costs.
Protect your care home from underinsurance
For most care providers, their property is one of their most valuable assets. An accurate reinstatement cost assessment can help ensure your buildings insurance reflects the true cost of rebuilding following a major loss.
Get in touch with Quality Care Group to arrange a professional reinstatement cost assessment for your care property.
